Flood Zone X vs. AE in Tampa Bay: Where You Need Flood Insurance (and Where You Don't)
What FEMA flood codes mean for your mortgage payment and coastal vs. inland Tampa home search.
Flood Zone X sits outside the high-risk 100-year floodplain, so mortgage banks do not require flood insurance there. Flood Zones AE and VE require mandatory flood policies on financed homes. Always check the home's Elevation Certificate before ruling any house in or out.
- Most inland homes in Carrollwood, Northdale, Lutz, and Wesley Chapel sit in dry Flood Zone X.
- Mortgage lenders require flood policies on every bank loan in Flood Zones AE and VE.
- Under FEMA Risk Rating 2.0, raised floor heights and smart vents cut flood bills fast.
- Many Zone X owners buy low-cost private flood coverage for heavy summer storms.
1. Deciphering FEMA Letters: Zone X, Zone AE & Zone VE
Big home apps often stick broad flood scores over entire zip codes. Even worse, they miss tiny creeks behind quiet yards. Checking real FEMA maps puts you in charge when shopping across Hillsborough and Pinellas:
- Flood Zone X: Low-risk land outside the main 100-year floodplain. Regular bank loans do not force flood insurance here.
- Flood Zone AE: High-risk flood zone with a 1% yearly flood chance. Buyers with loans must carry flood insurance at closing.
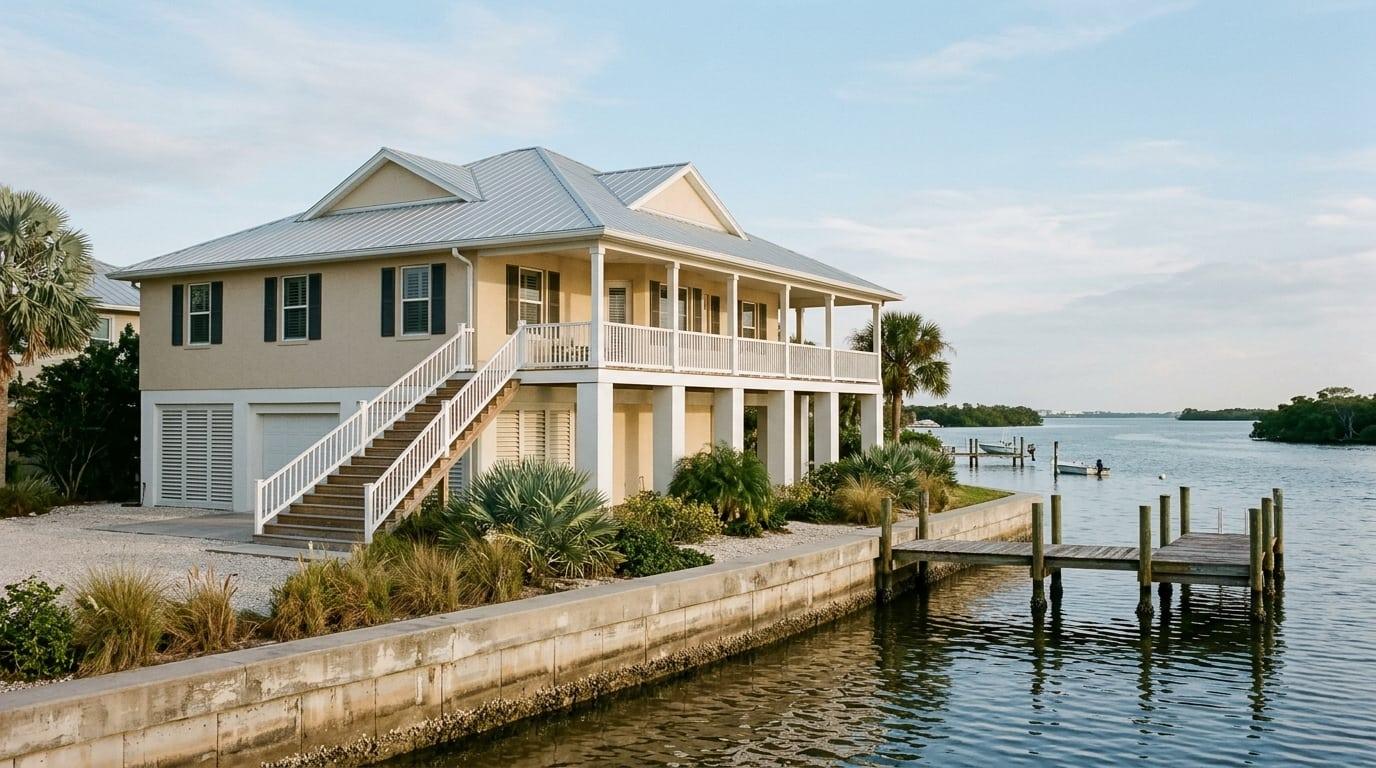
- Flood Zone VE: Open-coast wave zone along beaches and bay walls, calling for tall stilts and breakaway walls.
2. Why Elevation Certificates Drive Flood Costs
Two houses side by side in St. Pete or Davis Islands can differ by $4,000 a year in flood bills. Under FEMA Risk Rating 2.0, pricing tracks how high the main floor sits above the street and how far water sits from the wall. A block house raised four feet above flood height pays far less than a low 1962 slab.
- Check Smart Vents: Water-pressure vents in garages or lower walls cut Zone AE quotes cleanly.
- Watch the 50% Rule: Big remodels on low Zone AE homes costing over 50% of building value trigger full house raising rules.
3. Private Flood Quotes vs. Seller NFIP Policies
Never settle for just one flood price quote. Good Florida agents pull both government NFIP quotes and private carrier quotes together. Also check if a seller holds an older lower-cost NFIP plan you can take over at closing.
How Mark & Rachael Handle It
Before you write an offer, Mark and Rachael check FEMA flood lines for that single house lot. We ask for Elevation Certificates early so insurance pros run NFIP and private quotes right away.
See Live Homes or Talk With Our Team
Frequently Asked Questions
Should I carry flood coverage inside Flood Zone X?
Can buyers assume a seller's lower NFIP flood plan at closing?
Where do I find a house Elevation Certificate?
Explore Related Areas & Communities
Mark Davis
Commercial & Residential Advisor • Align Right Realty Carrollwood
Discuss Your Strategy With Mark Davis
Request customized comps, off-market listings, or a 1-on-1 strategy call.